Elvira Lopez de Lara Merida on looking beyond headline returns
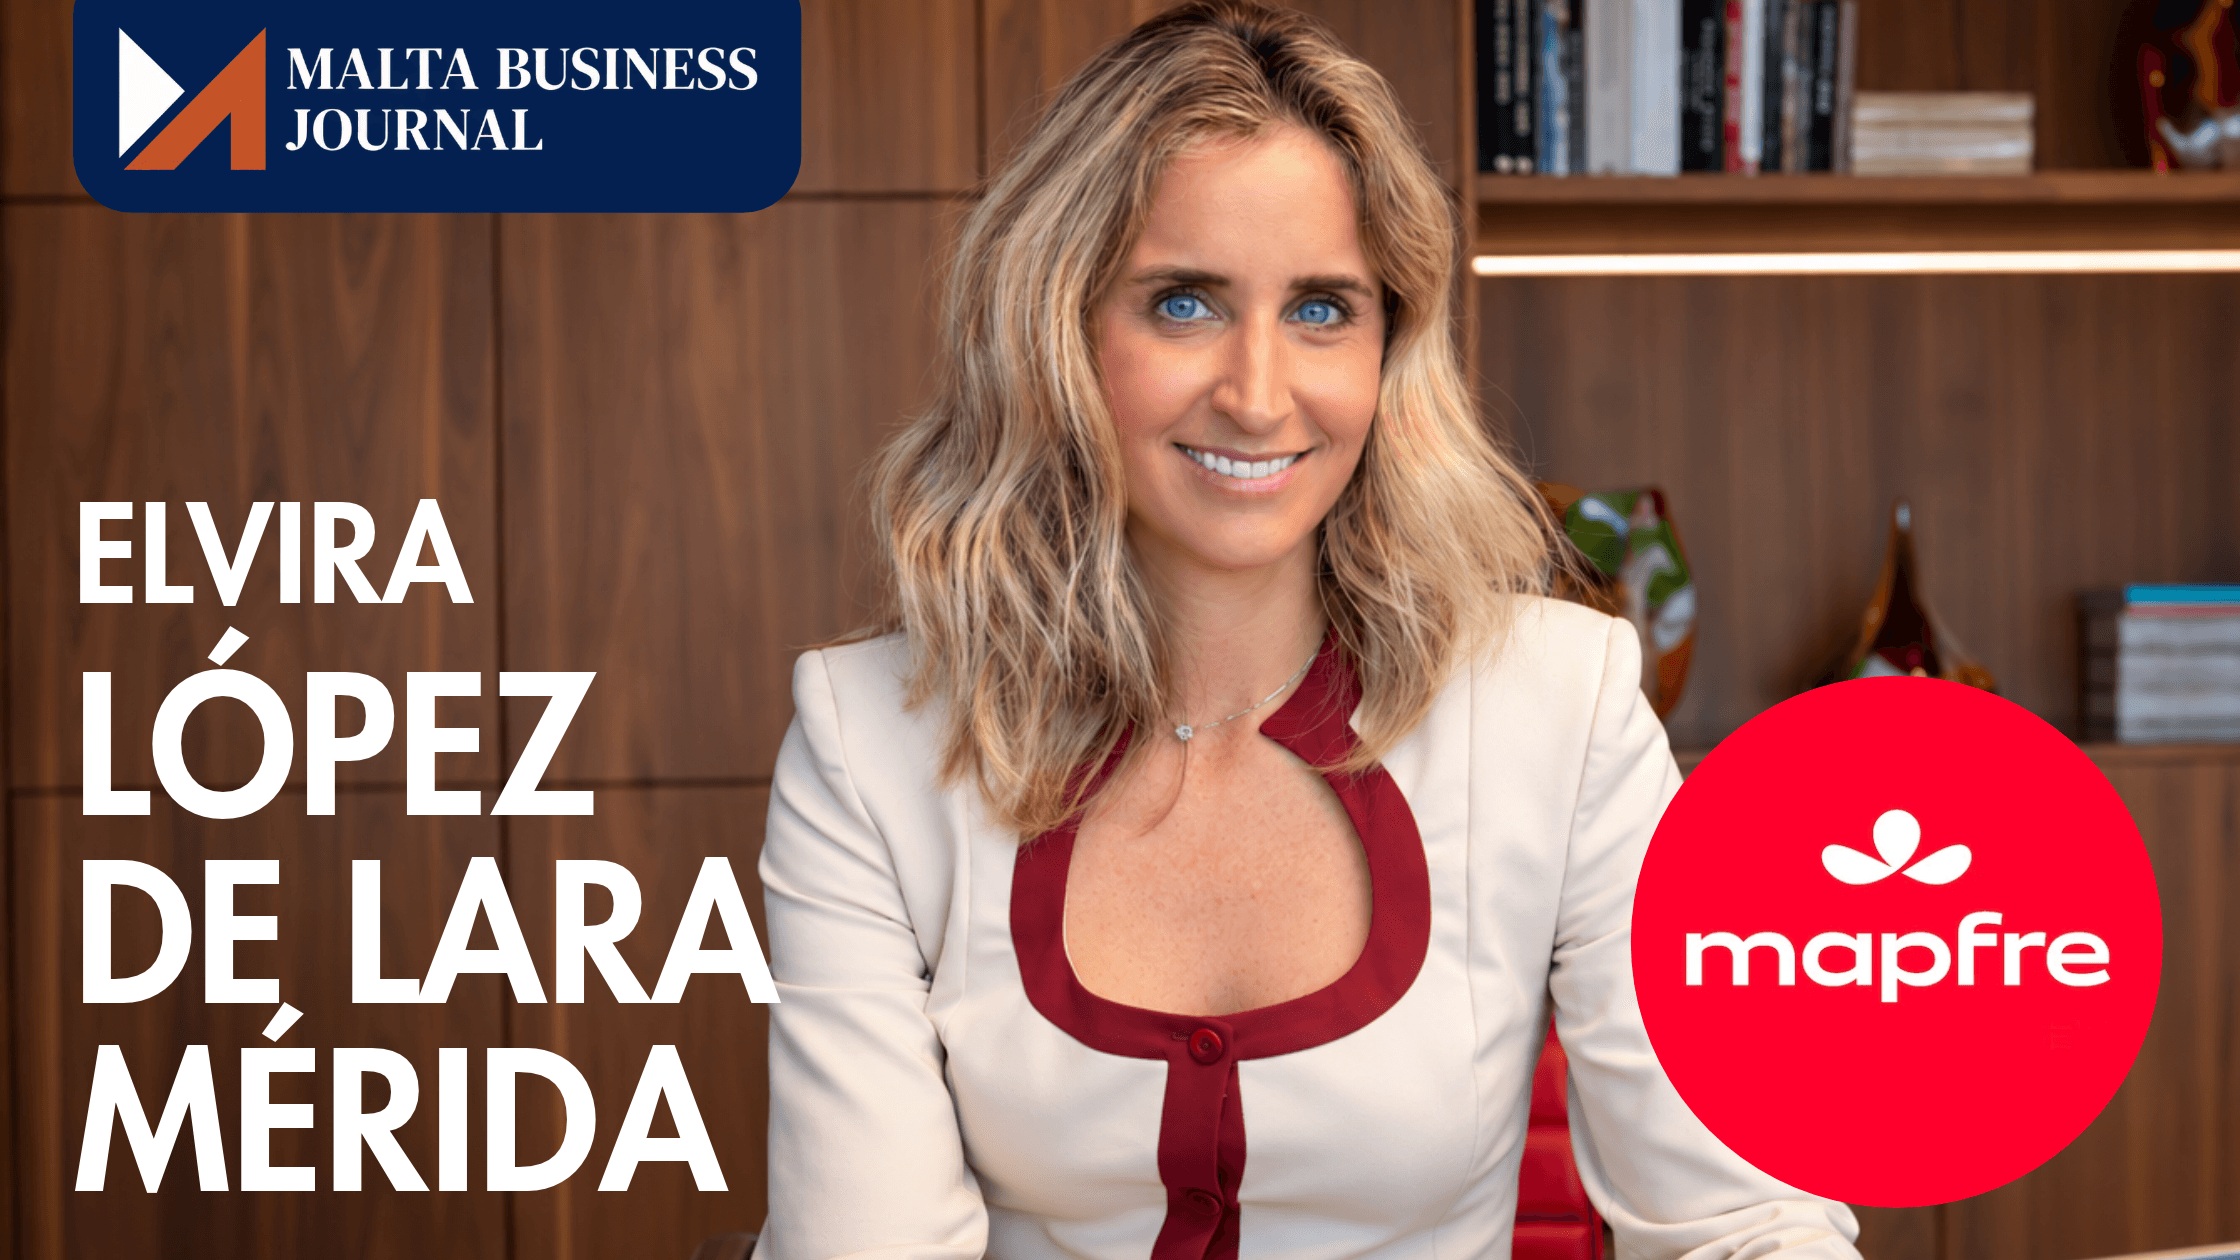
Elvira Lopez de Lara Merida, CEO of MAPFRE MSV Life, discusses how households in Malta can balance today’s financial pressures with long-term protection and retirement planning, and why clear advice matters more than headline returns.
Before discussing a product, Elvira Lopez de Lara Merida wants to understand the purpose of the money. The Chief Executive Officer of MAPFRE MSV Life places that question at the centre of financial planning, alongside what a household can afford and how long it can commit.
In this MBJ 1:1 interview, she connects immediate household pressures with decisions about protection and retirement. Her answers also set a standard for the industry: customers should be able to explain what they have chosen and why. That places a responsibility on providers to make the terms of a financial commitment understandable.
Looking towards 2027, she describes an approach built around realistic expectations and advice that continues beyond the initial sale.
A plan the household can keep
The first question is how families can make room for protection and retirement while meeting immediate commitments. Lopez de Lara Merida begins with the budget and a plan that remains manageable.
“I believe the starting point must be a realistic household budget. Long-term planning should support financial stability, not create additional pressure today.
“My approach would be to prioritise essential spending, maintain a buffer for unexpected expenses and identify the protection the family genuinely needs. Alongside that, I would encourage a manageable commitment to retirement saving, rather than an ambitious contribution that becomes difficult to sustain.
“This should not be an all-or-nothing decision. The aim is to protect today’s financial stability while keeping tomorrow’s needs in view. A plan must be affordable enough to continue and flexible enough to review as circumstances change.”
What a headline rate cannot explain
From affordability, the interview turns to the expectations attached to long-term products. Her focus is on what the product is designed to do and how clearly its terms are understood.
“I would encourage customers to distinguish between movements in interest rates and the purpose of a long-term financial product. The key question is not simply, “What return might I receive?” but, “What is this product designed to do for me, and over what period?”
“My priority is clarity about what is guaranteed, what depends on investment performance, what protection is included and what costs or restrictions apply. An illustration should never be mistaken for a promise.
“I believe customers should assess the whole proposition against their needs, rather than judge a long-term commitment by today’s headline rate alone.”
Making the protection gap a practical conversation
Asked how the industry can discuss gaps in cover without alarming customers, she frames the conversation around the life a family wants to preserve.
“I believe the conversation should begin with what people want to preserve: their family’s stability, their children’s opportunities and their financial independence.
“Rather than presenting alarming scenarios, I would ask practical questions. What commitments would still need to be met if an income were interrupted? What savings and existing cover would be available? What would remain uncovered?
“That makes the protection gap a planning question, not a source of anxiety. My responsibility is to help customers understand their choices, including affordability and the limits of cover. Success should mean that someone leaves the conversation feeling better informed and more in control, not more afraid.”
Preparing for more than one outcome
The discussion then turns to uncertainty in borrowing costs and savings returns. Lopez de Lara Merida places flexibility at the centre of the response.
“I would encourage customers to prepare for a range of outcomes rather than build their finances around a single forecast.
“For borrowing, that means understanding the terms of the loan and considering whether repayments would remain manageable under less favourable conditions. For savings, it means being clear about when the money will be needed, how accessible it must remain and what level of investment risk is appropriate.
“My guiding principle is to leave room to adapt. I would not want a customer’s financial security to depend on correctly predicting the next interest-rate decision or achieving an optimistic investment return.”
Defining the purpose before choosing the product
When asked which planning mistake customers should avoid, she is careful about the limits of the claim. Her concern is the order in which the decision is made.
“The mistake I would particularly encourage customers to avoid is choosing a product before defining the purpose of the money.
“I would not describe any one mistake as the most common without evidence. However, my advice is clear: do not let an attractive headline return or a tax incentive replace a proper assessment of suitability.
“I would start with the objective, the time horizon, the need for access to funds and the ability to accept investment losses. Only then would I consider the product. The right solution is not necessarily the one that looks most attractive today, but the one that fits the customer’s circumstances.”
Understanding at the moments that matter
Turning to financial confidence in Malta, she identifies the points when customers most need a connected view of their finances. Her test for good advice is whether the decision has been understood.
“In Malta, I would prioritise the moments when financial decisions become especially consequential: buying a home, starting a family, becoming self-employed or preparing for retirement.
“I would like advice to connect these decisions rather than treat borrowing, protection and saving as separate conversations. Customers should be able to understand how a commitment fits within their overall financial position.
“I would also put particular emphasis on plain explanations of costs, guarantees, risks and access to money. For me, providing documentation is not the same as achieving understanding. The real test is whether customers can explain, in their own words, what they have chosen and why.”
A lasting commitment towards 2027
The final question looks to 2027 and what would support more sustainable long-term investment. She addresses both the durability of the customer’s commitment and the evidence behind environmental claims.
“Looking towards 2027, I believe the priority should be to make long-term investment understandable, accessible and financially sustainable for the customer.
“I would favour manageable commitments, transparent costs and advice that continues beyond the initial sale. I would also welcome a stable framework that gives households and businesses confidence to plan, without suggesting that uncertainty can be eliminated.
“If sustainability also refers to environmental objectives, I would apply the same standard: clear explanations and evidence behind the claims.
“Ultimately, I want long-term investment to rest on informed decisions and realistic expectations, rather than short-term enthusiasm or a prediction about where interest rates will go next.”