Central Bank flags softer business conditions as property demand stays strong
Business conditions dip slightly but industrial production and tourism remain solid. Property demand stays strong while supply permits fall.
The Central Bank of Malta’s latest Economic Update points to an economy running at two speeds. Industrial production, services, and tourism are accelerating, but the broader business climate has lost some steam.
The Bank’s Business Conditions Index dipped marginally in August and now sits fractionally below its historic average. That slight softening contrasts with faster growth in industrial output and services production recorded in July.
Tourism continued to perform well in July, and retail activity also picked up. Consumer sentiment moderated in August but remained well above its historic average.
The property market tells a contradictory story. Final deeds and promise-of-sale agreements both increased in August compared with the previous month and the same month last year. Demand is clearly still there.
Supply, however, is tightening. Approved permits for residential and commercial buildings fell from July. Residential permits were also down year-on-year, while commercial permits held steady.
Inflation is easing. Annual HICP inflation dropped to 2.0% in August from 2.1% in July, well below the euro area's rate. Core HICP inflation excluding food and energy stood at 2.2%. The Retail Price Index also slowed, to 2.6%.
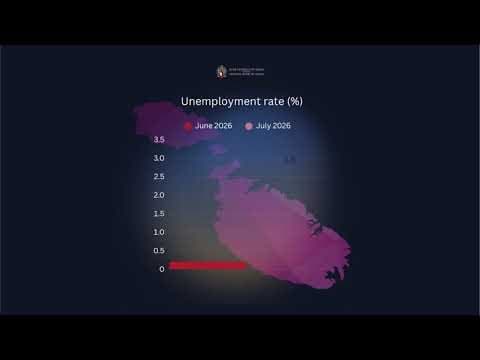
The labour market showed some signs of weakness. The unemployment rate held at 3.5% in July, unchanged from June but above the rate a year earlier. Consumers’ expectations of unemployment rose in August.
On the fiscal side, the Consolidated Fund recorded a larger deficit in July than a year earlier. Government expenditure increased faster than revenue.
For local businesses, the data carries a clear message: the economy is not losing altitude, but the lift has moderated. Strong tourism and property demand are offsetting softer business confidence. With inflation under control and spending still rising, the outlook is one of cautious equilibrium rather than acceleration.